What is a business trust? Meaning, Examples, and Key Differences
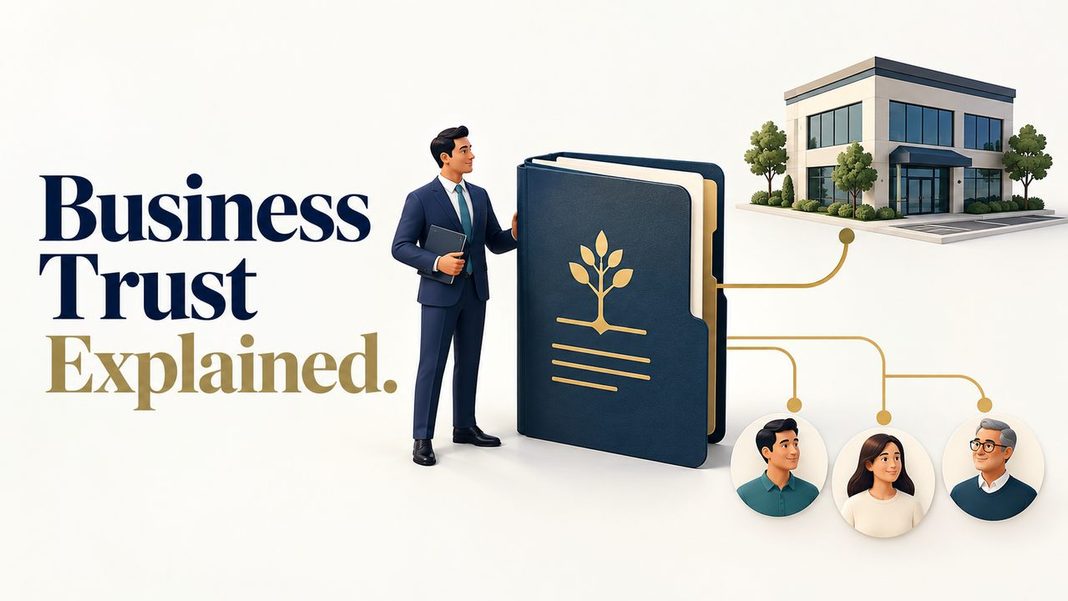
Quick answer: A business trust is a trust-based arrangement used to conduct business or manage commercial assets for beneficiaries. Trustees manage it under a governing document, while beneficiaries hold rights to its economic benefits. Its legal status, liability protection, and tax treatment depend on the applicable law and the arrangement’s actual structure.
If you are asking “what is a business trust,” you may be comparing business structures, planning an ownership transfer, or studying business history. The term has more than one meaning, which explains why some answers seem to contradict each other. This guide separates those meanings and explains the questions to ask before choosing a structure.
Legal and tax note: This article provides general educational information. Formation, liability, and taxation depend on your circumstances and applicable law; get advice from a qualified attorney and tax professional before acting.
Key Takeaways
- Trustees manage a business trust; beneficiaries hold the beneficial interests.
- A commercial trust and a family trust that owns business shares serve different purposes.
- Calling an arrangement a trust does not automatically make it tax-exempt or eligible for ordinary trust taxation.
- Liability protection depends on the governing law, documents, and conduct involved.
- Historical industrial trusts are a separate meaning of the term.
- Compare the full operating and administration costs with an LLC before committing.
Understanding what is a business trust in practice
A useful business trust definition is an arrangement in which property or business activity is managed under trust terms for beneficial owners. Its governing document sets out how decisions and economic benefits are handled. The statutory trust definition in Delaware law illustrates one legally recognized version, rather than a rule that applies everywhere.
The word “trust” describes a legal arrangement, not a promise that everyone involved is trustworthy. It also does not mean the arrangement is a bank or a professional trust company. A trust company may provide trustee services, while a business trust is the arrangement being administered.
The main roles
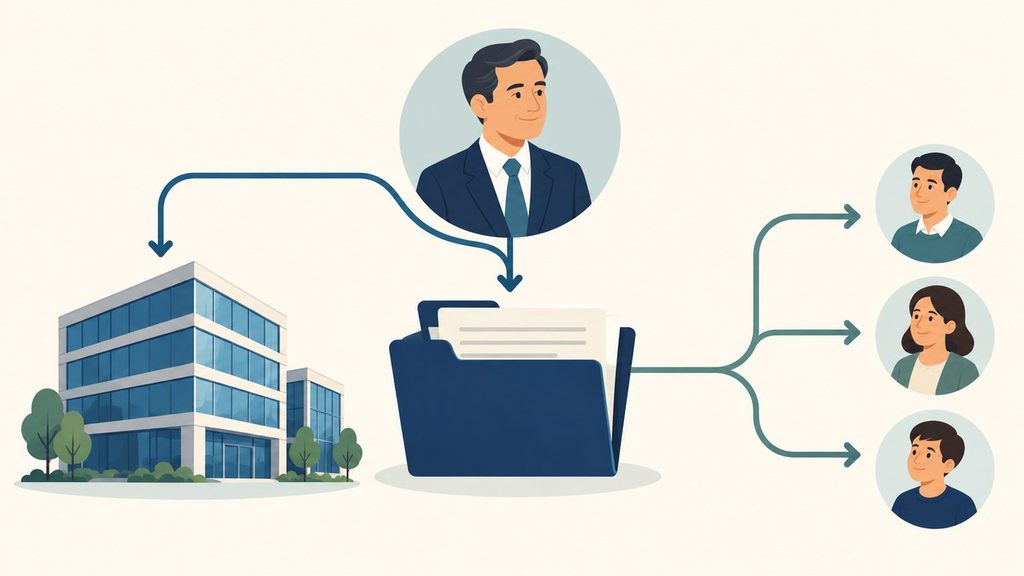
The definitions of trust participants and governing documents help explain who contributes property, who manages it, and who benefits. Keep these roles separate when reviewing a proposal, even when one person occupies more than one role.
| Role or document | Plain-language meaning | Question to ask |
|---|---|---|
| Settlor or grantor | Person who creates or funds a trust | What property is actually being contributed? |
| Trustee | Person or organization with management responsibilities | Who can sign contracts and authorize payments? |
| Beneficiary or beneficial owner | Person or entity holding rights to benefits | What distributions and information can they receive? |
| Governing instrument | Document establishing the arrangement and its rules | How are powers, succession, and disputes addressed? |
Being entitled to income does not necessarily mean you can approve every purchase or remove the trustee whenever you want. Ask for the relevant provisions rather than relying on a general description. Ownership rights and management powers need to be understood separately.
A simple hypothetical example
Imagine several investors want a commercial property managed through a trust arrangement. Their proposed documents name a trustee, describe the investors’ beneficial interests, and explain how available cash would be distributed. The trustee’s authority to lease, borrow, sell, or hire help would need to be established in those documents and under applicable law.
Now imagine the building needs an expensive repair before a distribution date. The practical question is whether the governing terms allow the trustee to retain cash, require approval, or follow another process. This example shows why reading the decision rules matters as much as knowing who receives the profits.
Business trust vs LLC: How do they compare?
Both structures can separate management functions from economic ownership, but they use different legal frameworks. An LLC has members and may be managed by its members or designated managers. A business trust uses trustees and beneficial interests, subject to its particular governing terms and law.
| Factor | Business trust | LLC |
|---|---|---|
| Ownership terminology | Beneficiaries or beneficial owners | Members |
| Management | Trustees or another arrangement allowed by governing law and documents | Members or managers |
| Core governing document | Trust agreement or declaration of trust | Operating agreement |
| Formation | Requirements depend on the type of trust and jurisdiction | State formation filing and applicable requirements |
| Federal income tax treatment | Requires analysis of the arrangement’s actual classification | Generally depends on member count and elections |
| Main comparison question | What specific advantage does this arrangement provide? | Does this structure meet the ownership and operating needs? |
The guidance on choosing a business structure explains why liability, taxes, and operating needs belong in the same decision. For an ordinary small business, I would start by comparing familiar options such as an LLC and a corporation. I would then ask what concrete problem a business trust solves better.
For example, “we want flexible management” is too broad to settle the choice. Ask whether the proposed voting rights, distribution rules, or succession provisions are difficult to achieve through an LLC operating agreement. That gives your adviser something specific to compare.
Before choosing any structure, clarify your business concept and operating model. A venture serving customers with employees and contracts raises different planning questions from an arrangement holding a defined investment. The legal structure should support how the venture will actually work.
Business trust vs family trust: Purpose matters
A family trust generally centers on holding and managing property for family beneficiaries. A commercial business trust centers on business or investment activity. The fact that relatives are beneficiaries does not, by itself, settle the arrangement’s legal or tax classification.
Consider a founder who places an ownership interest in an existing business into a family trust. That transfer does not automatically convert the operating company into a business trust. The company’s management documents and the trust’s ownership provisions would need to work together.
For a family business, separate the questions of who inherits the economic interest, who manages daily operations, and who can sell the business. These decisions may overlap, but they are not identical. Broader estate planning and tax strategy for business owners provides useful context for that discussion, especially when succession is the main goal.
How are business trusts taxed?
The legal name and federal tax classification are separate questions. Under the federal rules distinguishing business trusts from ordinary trusts, an arrangement formed to carry on a profit-making business may be classified as a business entity. It does not receive ordinary trust treatment merely because title is held through trustees.
An investment trust may require a different analysis, including whether its agreement allows investments to be varied. Consequently, “all business trusts pay corporate tax” and “all business trusts pass income directly to beneficiaries” are both unsafe blanket statements. A tax professional needs to examine the governing terms, activities, and applicable classification rules.
LLCs also require classification analysis, although their default rules are often easier to identify. The federal tax classification rules for LLCs generally treat a domestic multi-member LLC as a partnership and a single-member LLC as disregarded for income tax purposes unless corporate treatment is elected. Employment and certain excise taxes have separate rules.
Before funding a proposed arrangement, ask your tax adviser:
- What is its federal tax classification, and why?
- Which returns, elections, and owner statements will be required?
- Who reports income that is retained or distributed?
- What tax consequences could arise when assets are contributed?
- Which state and local obligations apply?
Watch for automatic tax-saving claims
Be cautious when someone claims a trust can eliminate tax while you continue controlling the business as before. The warning about abusive business trust schemes describes arrangements that create the appearance of giving up control without doing so in substance. Such arrangements provide no promised tax relief.
The answers to common trust taxation questions also explain that assigning earned income to a trust does not automatically shift the earner’s tax obligation. Ordinary personal living expenses do not become deductible simply because a trust pays them. Get an independent review of the claimed tax result before purchasing a packaged arrangement.
Does a business trust protect personal assets?
Some statutory arrangements provide limited liability, but the protection must be checked against the actual law and governing instrument. For example, Delaware’s beneficial-owner liability provision generally gives beneficial owners corporate-stockholder-style protection unless the governing instrument provides otherwise. That example does not establish identical protection in every jurisdiction.
Ask your attorney to assess owner liability, trustee liability, contractual guarantees, and the exposure of the business assets themselves separately. “Limited liability” does not answer all four questions. I would also ask how the proposed insurance and contract terms fit the arrangement before relying on a broad asset-protection claim.
What did “business trust” mean in history?
In business history, a trust can refer to a combination used to bring multiple companies under centralized control. This meaning is associated with industrial concentration rather than simply managing property for beneficiaries. Confusing it with a modern commercial trust can lead to a misleading definition.
The history of industrial combinations and antitrust legislation describes trusts dominating sectors such as oil, steel, tobacco, and railroads. Concern over their power helped lead to the Sherman Act in 1890. The relevant issue was how those combinations affected competition.
If you are answering a history assignment, focus on concentrated control and competition. If you are choosing a current business structure, focus on governance, ownership, liability, and taxation. A modern business trust is not automatically a monopoly merely because both use the same word.
How to evaluate or establish a business trust
There is no single formation checklist that works for every business trust. Use the following steps as a planning framework, then have a local attorney identify the legal requirements. Completing a template is only one part of the process.
1. Define the problem you want to solve
Write down whether your priority is investment management, ownership succession, decision-making authority, or another specific need. Then identify the assets, participants, and expected activities. A clear objective makes it easier to compare the trust proposal with other structures.
2. Identify the governing law and trust form
Ask whether the proposal is a statutory trust, a common-law arrangement, or an ordinary trust holding business interests. Have your attorney explain any filings, operating registrations, and trustee requirements that follow from that choice. Do not assume a document valid in one state works unchanged elsewhere.
3. Review governance before signing
Request clear answers on trustee appointment and replacement, borrowing powers, distributions, information rights, transfers, and termination. Also ask how conflicts between participants would be handled. If the answer depends on a particular clause, have that clause explained in plain language.
4. Plan funding and practical operations
Identify which assets will move and which permissions or documents need review before any transfer. Ask the bank, insurer, and relevant counterparties what they need to recognize the arrangement. Build the administration process around accurate ownership records and clearly authorized signatures.
5. Confirm taxes and ongoing responsibilities
Get the classification analysis and expected filing obligations before contributing property. Then assign responsibility for bookkeeping, tax filings, distributions, and required notices. A structure that nobody can administer reliably is a poor practical choice, however attractive it sounds.
Advantages, drawbacks, and costs to consider
The strongest reason to choose a business trust is a specific governance or investment need that it handles well. The weakest reason is a vague promise of secrecy, effortless protection, or tax elimination. Compare the proposed result with the cost of implementing and maintaining it.
| Potential advantage to evaluate | Tradeoff to investigate |
|---|---|
| Tailored decision and distribution provisions | Drafting quality and interpretation risks |
| A trustee-led management arrangement | Trustee selection, replacement, and compensation |
| Defined beneficial interests | Transfer rules, valuation, and investor expectations |
| A structure suited to a particular investment | Tax classification and additional regulatory review |
There is no reliable universal price or completion time for creating a business trust. Ask for an itemized estimate covering legal advice, tax analysis, filings, asset-transfer work, and ongoing administration. A low document fee tells you little about the total cost.
For a fair comparison, request the same scope of estimate for an LLC or corporation. Include what happens if a participant leaves, dies, or wants to sell. Those events often reveal whether the proposed arrangement is manageable over the long term.
Frequently Asked Questions
Is a business trust a corporation?
A business trust and a corporation are different legal forms. However, a trust-based arrangement may receive corporate treatment for tax purposes. Ask separately about its state-law form and its federal tax classification.
Can one person be both trustee and beneficiary?
Roles can overlap in some arrangements, but the permitted structure and consequences depend on the governing law and documents. Having both roles does not remove the need to distinguish management authority from economic rights. Ask your attorney whether the proposed overlap creates validity, conflict, or tax issues.
Can a business trust own an LLC?
A proposed trust arrangement may hold an LLC interest, subject to applicable law and the LLC’s governing documents. Before transferring an interest, check ownership eligibility, approval requirements, and any tax restrictions. Holding an LLC interest does not automatically change the LLC’s legal form.
Is a business trust revocable or irrevocable?
The label “business trust” alone does not answer that question. Review the governing instrument and applicable law to determine who can amend or terminate it. Also distinguish changing management provisions from taking contributed assets back.
Are beneficial interests always freely transferable?
No universal transfer rule applies to every arrangement. Review any consent requirements, eligibility restrictions, and procedures in the governing documents. Ask for an explanation of what a beneficiary can actually sell or transfer before relying on a certificate or ownership statement.
What happens if a trustee resigns or dies?
The governing terms and applicable law determine how a successor takes over. Before formation, ask who fills a vacancy and how signing authority and records will be updated. A practical succession process should address ongoing payments and decisions as well as the replacement appointment.
Conclusion: Choose the structure around your actual needs
The answer to “what is a business trust” starts with trustee management and beneficial ownership, but the decision requires more detail. Its usefulness depends on the arrangement’s purpose, governing terms, legal framework, and tax classification. Historical industrial trusts and family trusts holding business interests should be considered separately.
Start by listing your assets, intended owners, decision-makers, and succession goals. Bring that list to a qualified attorney and tax professional, and request a written comparison with an LLC or corporation. Choose the arrangement you can explain, afford, and administer with confidence.